How a Career Change Can Completely Shift Your Financial Plan

Many people think of a financial plan as something you create once and then follow for years.
In reality, your plan should evolve right along with your life.
A great example of this is a couple I worked with over several years—we’ll call them Grant and Rosalina.
Starting Out: Doing Everything Right, But Still Feeling Tight
When we first began working together, Grant and Rosalina were earning a solid combined income. However, like many families, they had competing priorities.
They were:
- Helping both daughters with college expenses
- Supporting them with cars
- Managing costs related to an unexpected legal situation
Because of this, their cash flow was tight for a number of years.
Our focus during this phase was not on maximizing large investment contributions, but on building a strong foundation:
- Optimizing their employee benefits
- Creating a realistic budget
- Planning for college costs
- Ensuring they had the right insurance coverage
- Finding efficient ways to save, even with limited extra income
This stage is more common than people realize. Financial planning is not always about doing more—it’s often about doing the right things with what you have.
The Turning Point: A Major Career Change
A few years later, everything changed.
Grant accepted a new position that came with:
- Significantly higher income
- Stronger employee benefits
- Access to an Employee Stock Ownership Plan (ESOP)
At the same time, both of their daughters had graduated from college, removing a major financial responsibility.
Suddenly, their entire financial picture looked different:
- More available income to save
- A higher tax bracket
- New opportunities—and new planning challenges
This is where many people make a critical mistake:
They continue following their “old” plan, even though their situation has changed.
Why We Needed to Rebuild Their Financial Plan
With these changes, it wasn’t enough to tweak a few numbers—we needed to revisit their entire strategy.
1. Adjusting for a Higher Tax Bracket
With increased income came increased tax exposure.
To improve tax efficiency, we:
- Shifted retirement contributions from after-tax Roth to pre-tax options
- Utilized Health Savings Accounts (HSAs) to further reduce taxable income
These moves helped them keep more of what they were earning while still preparing for the future.
2. Integrating New Benefits Into the Plan
Grant’s ESOP became a key component of their long-term strategy.
Once we incorporated it into their financial plan, we found something important:
With the combination of higher income, better benefits, and consistent planning, they were now in a position to potentially retire earlier than expected—while maintaining, and even improving, their lifestyle.
3. Aligning the Plan With Their Lifestyle Goals
Financial planning isn’t just about numbers—it’s about people.
During one of our conversations, Rosalina shared that her job had become increasingly stressful. She wasn’t sure she could continue in that role long-term.
Because we had already updated their financial plan, we were able to analyze different scenarios.
What we found was encouraging:
They could still achieve their long-term goals—even if Rosalina decided to transition to a lower-paying, but more fulfilling, role.
This is one of the most powerful aspects of planning:
Giving people the clarity and confidence to make life decisions, not just financial ones.
What This Means for You
Grant and Rosalina’s story highlights an important principle:
Your financial plan should grow and change with you.
Life events that should trigger a plan review include:
- A new job or promotion
- Significant income changes
- Children finishing school
- Changes in benefits or compensation structure
- Shifts in personal priorities or lifestyle goals
Without adjusting your plan, you may miss opportunities—or expose yourself to unnecessary risks.
A Financial Plan Is Not Static
A well-designed financial plan is not something you set once and forget.
It’s something you revisit, refine, and adapt over time.
In many cases, the biggest opportunities don’t come from doing more—they come from doing things differently as your situation evolves.
Grant and Rosalina didn’t just improve their numbers.
They gained flexibility, confidence, and the ability to make decisions that better aligned with the life they wanted to live.
Frequently Asked Questions
You should review your financial plan whenever there are major life or financial changes, such as a new job, income increase, changes in benefits, or shifting personal goals.
Yes. A career change can impact your income, taxes, retirement contributions, and long-term strategy. Updating your plan ensures these changes are aligned with your goals.
In many cases, yes. A higher income may make it beneficial to adjust contributions, especially for tax efficiency between pre-tax and Roth options.
A common mistake is continuing the same financial strategy without adjusting for new tax brackets, savings opportunities, or updated goals.
Most people benefit from reviewing their plan at least once a year, or sooner if there are significant changes in income, employment, or family situation.
Conclusion
Your financial plan should reflect where you are today—not where you were a few years ago.
As your income, career, and priorities evolve, your strategy should evolve with them.
Even small adjustments can create meaningful long-term improvements, especially when it comes to taxes, retirement planning, and overall flexibility.
If your situation has changed—or if it’s been a while since you’ve reviewed your plan—it may be worth taking a fresh look.
A thoughtful review can help ensure your plan continues to support both your financial goals and the life you want to live.
About the Author
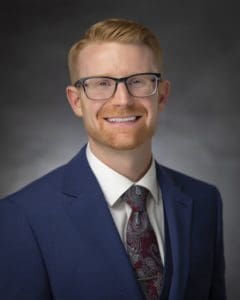
Andrew is a financial advisor at Redwood Wealth Management, where Andrew helps individuals and families create personalized financial strategies aligned with their long-term goals. With a focus on retirement planning, tax-efficient investing, and life transition planning, Andrew works closely with clients to adapt their financial plans as their lives evolve.
Andrew is passionate about helping clients navigate major life changes—such as career shifts, income changes, and retirement planning—so they can make confident financial decisions at every stage.